What If Every Website Started Accepting Cryptocurrency Instead of Credit Cards? The Internet's Payment System Could Change Forever
Imagine shopping online without entering your credit card number, waiting for a bank approval or worrying about international payment restrictions.
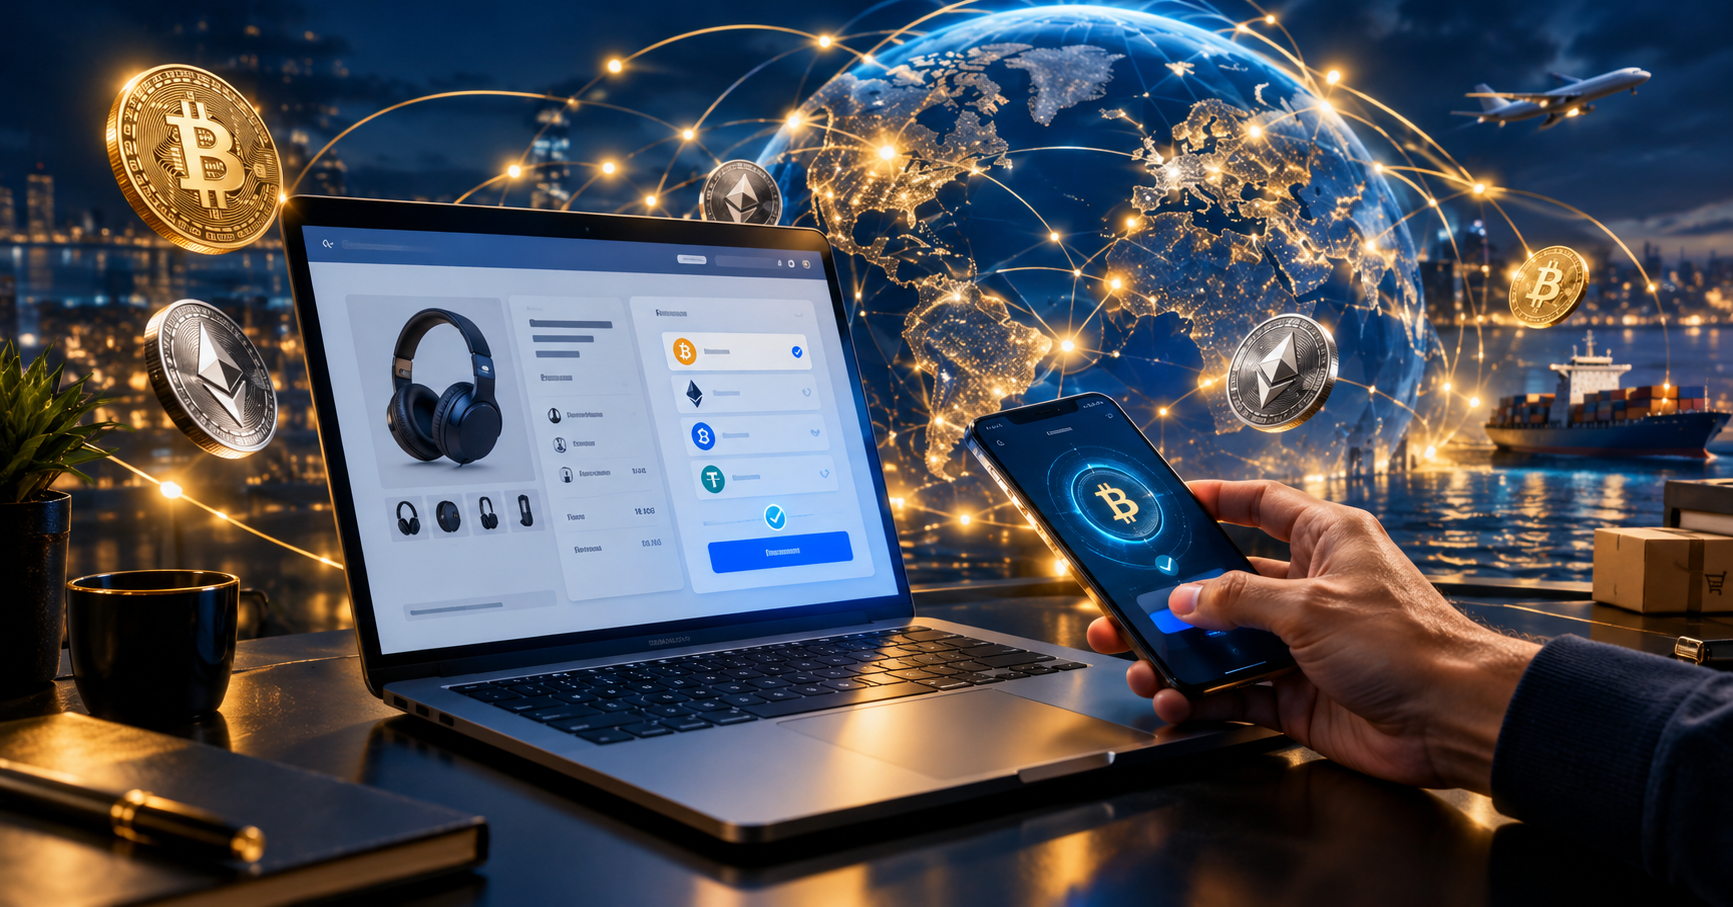
You simply open your crypto wallet, scan a payment request and send digital money. Within moments, the transaction is recorded on a blockchain.
Now imagine every online store, travel website, gaming platform and subscription service offering this option.
It could change how people buy things on the internet.
Cryptocurrency was originally promoted as an alternative form of digital money. But its role could become much bigger if online businesses begin accepting it alongside traditional payment methods.
The interesting question is not whether crypto can be used for online shopping. It already can. The bigger question is what would happen if cryptocurrency became a standard payment option across the entire internet?
Your Next Online Purchase Could Look Very Different
Today, most online shoppers use credit cards, debit cards, bank transfers or digital wallets.
A cryptocurrency checkout could work differently.
A customer selects a product, chooses a supported cryptocurrency and authorizes payment through a wallet. The merchant or payment processor verifies the transaction and processes the order.
Depending on the blockchain and payment provider, confirmation can happen within seconds or take longer.
Stablecoins such as USDC could be particularly useful because they are designed to maintain a relatively stable value against the US dollar.
For example, someone purchasing a $100 product could pay using approximately 100 USDC, rather than using a cryptocurrency whose market price might change significantly during checkout.
This could make digital currency payments more practical for everyday purchases.
Could Online Shopping Become Cheaper?
One of the biggest reasons businesses are exploring cryptocurrency payments is transaction cost.
Traditional card payments involve several participants, including payment networks, banks and processors. Their fees can reduce the amount merchants actually receive.
Blockchain payments may offer alternative settlement methods, particularly for international transactions.
For a business selling products across several countries, stablecoin payments could potentially simplify how money moves between customers and merchants.
However, cheaper transactions are not guaranteed. Blockchain network fees, payment processor charges, currency conversion and compliance costs still matter.
The real benefit would depend on the payment system being used.
Small Businesses Could Reach Customers Around the World
Imagine a small business in India selling digital products to customers in Europe, America or Singapore.
With traditional payment systems, international transactions can involve currency conversion, banking intermediaries and settlement delays.
A cryptocurrency payment system could give that business another way to receive money from overseas customers.
This is particularly interesting for freelancers, software companies, online gaming platforms and digital service providers.
It could also make cross-border payments more accessible to people who face difficulties using traditional banking services.
Big Companies Are Already Exploring This Future
This is no longer just a theoretical discussion.
In January 2026, reporting on a PayPal-backed merchant survey found that around four in ten surveyed merchants already accepted cryptocurrency at checkout. The survey covered approximately 620 payment decision-makers, so its findings should not be treated as representative of every business worldwide.
In June 2026, Checkout.com announced stablecoin payment acceptance for eligible enterprise merchants through its partnership with Coinbase Payments.
Deloitte has also projected that stablecoin-enabled US retail purchases could exceed $200 billion by 2030. This is a forecast, not a confirmed future outcome.
These developments suggest that payment companies are increasingly exploring ways to connect blockchain technology with everyday commerce.
Would Credit Cards Disappear?
Probably not anytime soon.
Credit cards offer something customers already understand: familiar checkout experiences, established dispute processes, fraud protection and widespread merchant acceptance.
Cryptocurrency payments face different challenges.
For example, sending funds to the wrong blockchain address can be extremely difficult or impossible to reverse. Some networks also experience congestion or changing transaction fees.
Customers may also hesitate to spend Bitcoin or other volatile cryptocurrencies because their market value can change significantly.
This is one reason stablecoins could have a more practical role in everyday online shopping.
Instead of replacing every existing payment method, cryptocurrency may become another option alongside cards, bank transfers and digital wallets.
What Could Go Wrong in a Crypto-Powered Internet?
A world where every website accepts crypto would also introduce new risks.
- Scams and fake payment addresses: Criminals could create fraudulent checkout pages to steal customers' funds.
- Lost transactions: Mistakes involving wallet addresses or networks could result in permanent losses.
- Privacy concerns: Public blockchain transactions may reveal payment patterns that users would prefer to keep private.
- Regulatory challenges: Businesses would need to follow applicable financial, tax and consumer-protection rules.
- Refund complications: Returning a crypto payment may require a separate transaction and clear refund policies.
These problems would need reliable solutions before cryptocurrency could become a truly mainstream online payment method.
Could Cryptocurrency Become the Internet's New Payment Language?
The most interesting possibility is that customers may eventually stop thinking about which payment technology is being used.
They will simply expect their purchases to work.
A website might accept cards, bank transfers, stablecoins and other digital currencies through one checkout system. Behind the scenes, payment providers could handle conversion, settlement and verification.
Visa has already been expanding its stablecoin initiatives, including settlement experiments involving USDC. This shows how traditional payment networks may connect blockchain technology with existing commerce rather than disappear.
The future of online payments may therefore be less about cryptocurrency defeating banks and more about different financial systems working together.
Final Thoughts: Will the Internet Eventually Run on Crypto?
If every website started accepting cryptocurrency, online shopping could become more flexible, international payments could gain new options, and businesses might reach customers who struggle with traditional payment systems.
But there is still a long way to go.
Security, regulation, refunds, customer trust and ease of use will determine how quickly these payment methods grow.
One thing is becoming clear: cryptocurrency is no longer being discussed only as an investment.
It is increasingly being explored as a way to move money.
And perhaps the biggest change will come when people stop asking whether a website accepts crypto and start expecting it to be there.
The Bottom Line
If every website accepted crypto, online shopping would become more flexible, cross-border payments would gain new options, and small businesses could reach global customers more easily.
Stablecoins like USDC could play a major role in everyday purchases due to their price stability.
But crypto won't replace credit cards anytime soon. Risks like scams, irreversible transactions, privacy concerns, and regulatory challenges remain.
The real future may not be crypto vs. banks — but both working together behind the scenes.
About CoinAINews
CoinAINews Editorial Team covers cryptocurrency regulation, blockchain technology, digital asset markets, traditional finance, and developments shaping the global tech industry.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial or investment advice.